It can also feel like someone suddenly started speaking a completely different language.
Earnest money.
Due diligence.
Appraisal.
Seller concessions.
FHA.
VA.
Conventional.
Closing costs.
Underwriting.
And somehow you're supposed to understand all of this while making one of the biggest financial decisions of your life.
That's why when I work with a first-time buyer, my goal isn't simply to unlock doors and show houses.
I want you to understand what you're doing and why you're doing it.
Here are some of the things I want my Tooele County buyers thinking about before we ever write an offer.
1. Your Maximum Approval Isn't Necessarily Your Comfortable Budget
One of the first conversations should happen with your lender.
But there are really two numbers to think about:
What can you qualify for?
and
What payment are you actually comfortable making every month?
Those aren't always the same number.
Your mortgage payment also isn't your only housing expense.
Depending on the property, you may have taxes, homeowners insurance, HOA fees, utilities, maintenance and future repairs.
I would much rather help you find a home that fits your life than push you toward the maximum number on your approval letter.
2. Understand Your Loan Options
Different buyers may have different financing options.
FHA
FHA financing can be a useful option for some buyers, particularly buyers who don't have a large amount available for a down payment.
HUD states that FHA down payments may be as low as 3.5% for qualifying borrowers. FHA loans also include mortgage insurance, and both the borrower and property must meet applicable requirements.
VA
If you're an eligible Veteran, service member or qualifying surviving spouse, a VA-backed home loan can be an extremely valuable benefit.
Eligible VA buyers may be able to purchase with no down payment, subject to the property's appraised value and lender requirements, and VA-backed loans don't require monthly private mortgage insurance. Some borrowers pay a VA funding fee, while certain borrowers are exempt.
Conventional
Conventional financing can also be a strong option depending on your credit, down payment, financial profile and the property you're purchasing.
There isn't one loan that's universally “best.”
That's why I want my buyers working with a knowledgeable lender who can show them their actual options.
My role is to understand enough about those options to help us structure the real estate side of the transaction intelligently while leaving mortgage advice to the lender.
3. Don't Just Look at the Pretty Parts of the House
When we walk through homes, it's easy to focus on countertops, flooring and paint.
Those things matter.
But I also want you asking questions like:
How old is the roof?
How old is the furnace and air conditioner?
What is the condition of the water heater?
Has the basement been finished?
Was the basement permitted?
Were major additions permitted?
Are there warranties that transfer?
What does the seller's property disclosure tell us?
Are there signs of water intrusion or previous repairs?
What major expenses might I encounter during the first several years of ownership?
A beautiful kitchen doesn't make an aging HVAC system disappear.
4. This Is Why Inspections Matter
The inspection period isn't something I want you casually checking off your list.
This is your opportunity to learn more about the home you're buying.
No home is going to be perfect.
The goal isn't necessarily to produce a giant list of tiny cosmetic issues and demand that the seller fix everything.
We want to identify issues that could materially affect the property, your finances or your willingness to purchase it.
Then we can decide how to respond based on the contract and circumstances.
5. You Need to Know Your Deadlines
Once you're under contract, things can start moving very quickly.
I don't want my buyers wondering:
“What happens now?”
I want you to know which deadlines are coming, what decisions need to be made and who is responsible for each part of the transaction.
That's part of how I approach communication.
You shouldn't need to become a real estate expert to buy your first house.
But you should understand what's happening with your transaction.
6. Negotiating Isn't Always Just About Purchase Price
This is another area where first-time buyers can get surprised.
Negotiation may involve much more than simply offering $5,000 or $10,000 below the asking price.
Depending on the situation, we might consider:
-
Purchase price
-
Seller-paid closing costs
-
Rate buydown assistance
-
Repairs
-
Home warranties
-
Closing dates
-
Possession
-
Other contract terms
Before writing an offer, I also want to understand the seller.
Why are they moving?
How long has the home been listed?
Have they reduced the price?
Is timing important?
Are there other offers?
The more we understand about the situation, the more intelligently we can structure your offer.
Your First Home Doesn't Have to Feel Overwhelming
Buying a home is a big deal.
You're not supposed to already know everything.
That's part of what I'm there for.
I want you to come away from your purchase feeling like you understood your options, your interests were protected and you had someone keeping track of the details along the way.
Thinking about buying your first home?
You don't have to wait until you're ready to make an offer to reach out.
Let's talk through the process, connect you with a lender if needed and figure out what your next step should be.
No pressure. Just information.
Sarah Kerchner
Realtor
Your Home Base for Every Adventure
FROM OUR BLOG
Why Your List Price Matters When Selling a Home in Utah
If you're thinking about selling your home in Tooele County or anywhere in Utah, there is one number I don't want you choosing based on emotion: Your list price. I understand why sellers want to start high. You love your home. You've invested money into it. Maybe you've upgraded the kitchen, finishe
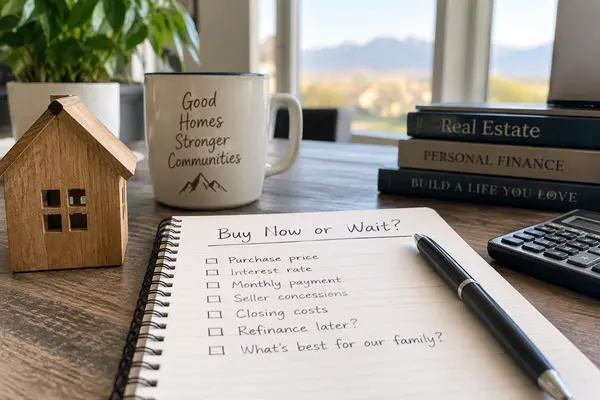
Should You Buy a Home in Tooele County Now—or Wait for Interest Rates to Drop?
Should You Buy a Home in Tooele County Now—or Wait for Interest Rates to Drop? One of the most common questions I hear from buyers right now is: “Should I buy now, or should I wait for interest rates to come down?” It’s a completely understandable question. Your interest rate has a major impact on y
Tooele County Events: What’s Happening September 2026
Tooele County Events: What’s Happening September 2026 If you’re looking for things to do in Tooele County in September 2026, you’ve come to the right place! September is packed with community events, farmers markets, live entertainment, family activities, festivals, and plenty of opportunities to ge