Realtor and CPA here. On November 2, 2026, home appraisals for most loans switched to a new report. Most buyers and sellers won’t hear about it until the appraisal is sitting on their kitchen table. Here’s the short version.
What changed
If your loan goes through Fannie Mae or Freddie Mac (that’s most conventional loans), new appraisals now use a redesigned report called UAD 3.6. It replaced the old forms on November 2, 2026.
The appraisal’s job didn’t change. It’s still an independent opinion of what the home is worth. The report is just a lot more detailed.
What’s new on the report
- Inside and outside are rated separately. The appraiser now gives the home’s interior and exterior their own condition ratings.
- Kitchens and bathrooms are reported room by room. Each one is noted as updated or not.
- Energy and disaster features have their own fields. Things like energy-efficient upgrades now have a dedicated place on the report.
- One form for every property type. The old separate forms for houses, condos, and so on were replaced by one report that adjusts to the property.
The transition
- Some lenders got an exception and can keep using the old format for a while, through May 19, 2027. The old format is fully retired June 28, 2027.
- FHA loans: the new format is optional for now. FHA hasn’t set a required date, so FHA appraisals may still come on the old form.
- The cutoff is based on when the appraisal is submitted, not when you applied for the loan.
Nothing I found says the new report raises or lowers values, or changes appraisal fees or timelines. If you’re wondering about timing or cost, ask your lender.
If you’re selling
Make an update list. Write down every update to your home and the year you did it: roof, furnace, water heater, kitchen, bathrooms, flooring, windows. Keep receipts if you have them.
Give the list to your agent to share with the appraiser. Facts, not a number you’re hoping for. With the report now going room by room, a clear list helps the appraiser see what’s actually been done.
If you’re buying
- Read the whole report, not just the value. Check the details: square footage, bedrooms, updates, condition.
- If a fact is wrong, tell your lender. Mistakes can be corrected.
- An appraisal is not a home inspection. The appraisal is for the lender and is about value. The inspection is for you and is about the home’s condition. You want both.
Questions?
Buying or selling in Tooele or Salt Lake this winter? Text me at 714-307-5107.
Selling: kerchnercohomes.com/sell | Buying: kerchnercohomes.com/buy
Sarah Kerchner | Realtor and CPA | KW South Valley
Sources
FROM OUR BLOG
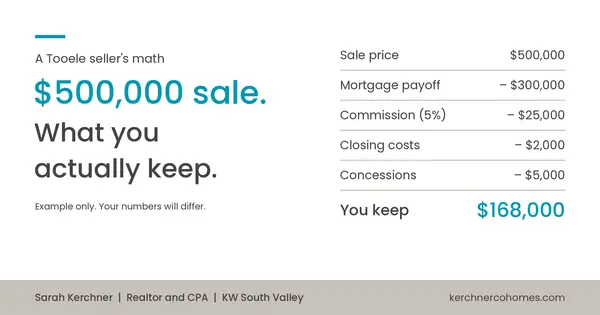
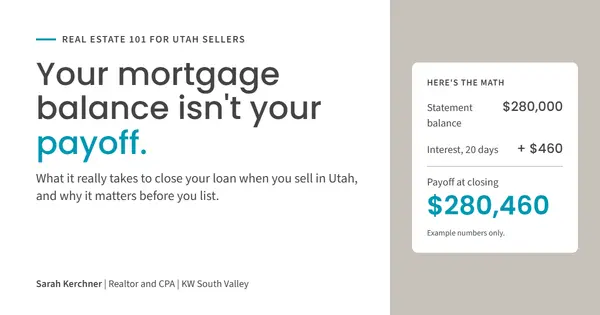
Your Mortgage Balance Isn't Your Payoff: What Utah Sellers Should Know
Realtor and CPA here. When I ask a Utah seller what they owe on their house, most of them read me the balance off their mortgage statement. Close, but that's not your payoff. And your payoff is the biggest line between your sale price and what you actually keep. Here's the difference, and why it mat
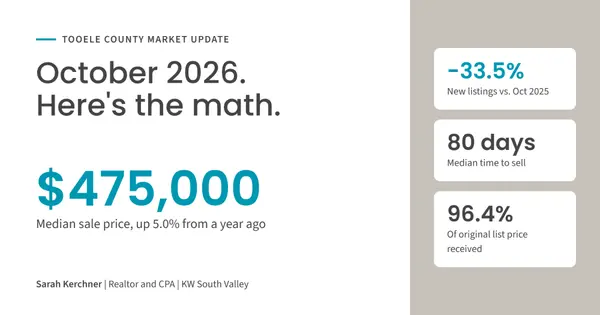
Tooele County Housing Market Update: October 2026
Realtor and CPA here. Every month I pull the Tooele County numbers so you don't have to. Here's what happened in October 2026, and what it means if you're thinking about selling. The short version: prices went up, but a lot fewer people listed, and homes are taking almost three months to sell. Price
November 2026 Events in Salt Lake County, Utah
November 2026 Events in Salt Lake County, Utah Looking for things to do in Salt Lake County this November? From holiday markets and festive light displays to live entertainment and family-friendly activities, there's plenty happening throughout the valley! Here's your guide to November 2026 events i